RHB etiketine sahip kayıtlar gösteriliyor. Tüm kayıtları göster

18 Şubat 2014 Salı

The Edge-Lipper Fund Awards 2014: Who's the BEST among all?

For unit trust industry, The Edge-Lipper Fund Awards was an annual event to showcase their best performing funds. It was like Oscar Awards for unit trust fund houses. This year there were a total of 47 awards presented. Who is the BEST ?


Let's refer to below table:


And the BEST Group Awards goes to...

Congratulations to Amanah Mutual Berhad !!!

8 Ekim 2012 Pazartesi

RHBRI Market Outlook & Strategy 4Q2012: Stormier Outlook


RHB research institute (RHBRI) is of the view that it could still be a choppy few months for the equity market in the 4Q given weakening economic fundamentals in the major world economies and fears of an imminent general election on the home front. Whilst more rounds of quantitative easing have been unveiled in the developed world, the big question in investors’ minds is how all these quantitative easing measures will translate to better global economic outlook. Having said that, equity still stands up vis-a-vis the unappealing returns of the alternative asset classes, such as cash and bonds and any good news is still likely to prompt a rally in equities.


How was Malaysia fared?
And, what's the strategy now?
Thus far, Malaysia has fared relatively well in the global financial crisis, and this is partly on account of low reliance on foreign funding of its banking system and more importantly, the progress in the implementation of the Economic Transformation Programme to boost domestic demand and cushion the economy against the downside risk from the external sector. As a result, the economy has bucked the trend and its real GDP growth is projected to pick up to +5.4% in 2013, from +5.0% estimated for 2012. This will translate to sustained earnings growth of around 6.0% in 2013 to create new shareholders’ values for investors.


We believe after a phase of correction and consolidation, the market will come back as the huge bond purchase programmes in the Eurozone and the US will push investors out of low-yielding cash and bonds over time into riskier assets such as equities. As the general election could be delayed to March 2013, our end-2012 FBM KLCI target remains unchanged at 1,690. Assuming global situations stabilize in six to nine months time and the global economic recovery is intact, our end-2013 FBM KLCI target is 1,815, based on 15x 2014 earnings.


Whilst our core strategy remains defensive, we believe investors would still need to accumulate fundamentally-robust stocks on weakness in order to outperform the market. In addition, as the search for yield will likely remain a key driver for both retail and institutional investors in the 4Q, high divided-yielding stocks will also continue to outperform the market, in our view. Sector-wise, our key overweight are telecommunications and banking, although we also have an overweight stance on the utilities and healthcare sectors.


Source: RHBRI research report

7 Eylül 2012 Cuma

RHBRI 4Q12 Market Strategy: Stay Defensive And Buy On Dips To Outperform The Market

Given the persistent headwinds from the external sector and general election overhang on the home front, we are of the view that the market will likely be stuck in a range-bound trading pattern in the 4Q. Consequently, we believe investors would still need to accumulate fundamentally-robust stocks on weakness in order to outperform the market, while staying defensive on the core holdings will provide greater stability to the portfolio performance.
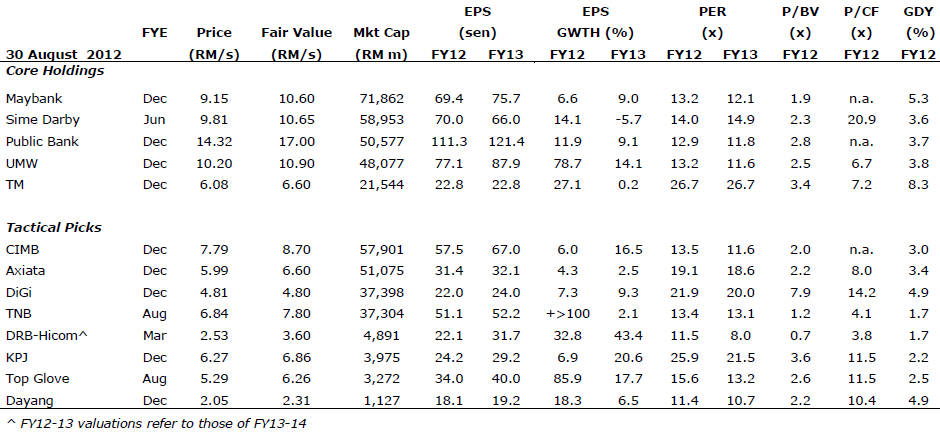
In addition, as the search for yield will likely remain a key driver for both retail and institutional investors in the 4Q, high divided-yielding stocks will also continue to outperform the market, in our view. A list of our top picks is reflected in table below, which includes “buy on weakness” tactical stocks.


Which Sector to look at?
Sector-wise, our key overweights are telecommunications and banking, although we also have an overweight stance on the consumer, utilities, gaming and rubber gloves under the healthcare sector (see table below). We expect the high-yielding telecommunications stocks to remain relatively defensive for equity investors under the current market environment.


The banking sector, on the other hand, carries a 34.7% weighting in the bellwether index and, in our view, cannot be ignored, given the better-than-expected recovery in earnings momentum over the last two consecutive quarters. The year-to-date annualized loan growth stood at 11.9%, ahead of our and the consensus forecasts of 10-11% and 8-9% and the pipeline of corporate deals remains healthy. This suggests that banking earnings could continue to surpass expectations in the quarters ahead, which coupled with decent valuations and dividend yields vis-a-vis the FBM KLCI benchmark, would bode well for share price performance in the 4Q, in our view.

Source: RHBRI research report

3 Temmuz 2012 Salı

RHBRI: Market Outlook & Strategy 2H2012


In our view, the equity market will likely be stuck in a range-bound trading pattern for now, but will likely trend up as global economic uncertainties clear out towards the later part of the year. Investors’ key worries include :


  1. worsening of the euro-debt crisis that remains unresolved
  2. fears of China’s and India’s economies crashing down into a hard landing; and
  3. the risk of US falling off the “fiscal cliff”.

External Volatility And Impending Election 2 Key Headwinds

On the home front, the major event to watch out for is the impending general election that could also create volatility to the local bourse given the uncertain election outcome. Nevertheless, we believe the market will eventually trend higher towards end-2012, premised on:
  1. the ECB making a more decisive move to mutualise the debts of Eurozone governments;
  2. China policymakers ease policies substantially and its economic growth re-accelerates;
  3. US Congressional leaders cobble together some deals to mitigate the impact from the “fiscal cliff” and allay the fear of its economy falling off the cliff; and
  4. domestically, the general election produces a result where the ruling coalition party remains in control of the government.

Meanwhile, global financial markets are still likely to be awash with liquidity as central banks in advance countries have pledged to maintain extremely loose monetary policy and could unveil more quantitative easing programmes to support economic growth should the situation warrant. 


On the home front, the economy is more resilient than feared and we expect real GDP growth to stage a modest rebound to 4.7% yoy in the 2H, from +4.4% estimated for the 1H. In the same vein, net EPS growth for the market is projected to recover to +10.8% in 2012 before moderating to +7.8% in 2013. Consequently, we are maintaining our end-2012 FBM KLCI target at 1,650 based on 14.6x 2013 earnings.


Given global macro headwinds and general eletion risks on the home front, we believe it pays for the more discerning investors to hold some defensive stocks that have strong cash flows to pay sustainable dividends in their portfolios. In addition, we believe investors would still need to accumulate fundamentally-robust stocks on weakness in order to outperform the market. Sector-wise, our key overweight are telecommunications, consumer and banking, although we also have an overweight stance on the utilities, gaming and semiconductor sectors.


Source: RHB Research Institute