tax relief etiketine sahip kayıtlar gösteriliyor. Tüm kayıtları göster

3 Aralık 2015 Perşembe

PRS Funds List Update and How to make PRS Transfer ? (Dec 2015)

Since the first PRS fund was launched in year 2012, many Malaysian already invested in it because of the PRS Tax Relief and PRS Youth Incentive given by the government. After awhile, many of us started to compare different funds from different PRS providers. It's very normal. So, the information below may helps you.


First, there are still 8 approved PRS providers in the market. But, number of funds already increased to a total of 50 PRS funds for us to choose from. CIMB-Principal has the most number of funds with 10, while RHB has the least at 3 only. Please refer to below picture.


Can I transfer from one provider to another?
Answer is YES. This is a stark different if comparing to normal unit trust investment, whereby investors cannot simply change company. In unit trust investment, an investors wish to change company must redeem and buy again. Coupled with higher sales charge imposed by unit trust investment, investors will be at the losing end.

However, with the forming of centralized administrator called Private Pension Administrator (PPA), PRS investors can request to transfer their funds from one PRS provider to another provider easily with minimum fees. Please refer to below table of the fees imposed for each transfer transaction:


* Please take note that the RM25 transfer fee imposed by PPA was waived until further notice


Any conditions before an investor is allowed to make a transfer?

  • Transfers are permitted per PRS Provider once only in a calendar year;
  • The first transfer is being made after one full year from the first contribution to any fund under any scheme managed by the Transferor Provider;
  • There had been no prior transfer with the Transferor Provider in that calendar year;
  • There is sufficient units in the fund(s) selected by the member for transfer;
  • Each transfer request is only between two PRS Providers which must involve a transfer of one or more funds from the Transferor Provider to one or more funds of the Transferee Provider; and 
  • All accrued benefits to be transferred from a particular fund must be transferred correspondingly to one other fund managed by the Transferee Provider. 

* Transferor = the PRS provider that you want to transfer money OUT
* Transferee = the PRS provider that you want to transfer money IN

Example, if you want to transfer your PRS funds from Public Mutual to Affin Hwang. The transferor is Public Mutual and the transferee will be Affin Hwang.

You may download the PPA transfer form here and submit to the PRS provider that you want (Transferee) together with their account opening form.


This article was contributed by Alex Yeoh, a licensed financial planner and corporate PRS distributor who represents multiple PRS providers.

You may contact Alex Yeoh via email alexyeoh@vka.com.my or follow his Facebook fans page.

23 Ekim 2015 Cuma

[Budget 2016] The "Diabetes-Free" Budget...

As expected, the Budget 2016 this round will concentrating on how to increase revenue of Government and spending cut due to lower oil revenue and subdued economic situation be it locally or globally.


Well, this is a "diabetes-free" budget without any "sugar" being dished out. Generally, it's not something to cheer about especially to those high income earners and businesses. In summary, please refer to below self-explained picture:


It's not so good to earn too much next year onward. High income earners are "forced" to care more about the society by paying more tax.


For those who have family and children, you are the main beneficiary of the budget this round. With higher tax relief being given, you can save more tax and hopefully this could help you to cope with rising cost of raising a child :)


BR1M is going to continue for another year (until the next election?) and with higher amount. Anyway, the quantum of Rm50 increase could really help you to counter the effect of GST ???


This will be another impact to businesses in Malaysia, especially to SME / SMI. Based on statistic, the most heavily affected industries will be manufacturing and plantation sectors. Glove makers (Top Glove, Supermax, Hartalega...) and planters (Sime Darby, Felda, IOI Corp...) would had some hard time moving forward. 

25 Nisan 2015 Cumartesi

Personal Tax Relief for YA2014

Coming to the last weekend of personal income tax e-filing (if without any extension period), here is the updated list of various tax relief granted for your reference. Not much changes from YA2013, except on the following items:

  • NO more special tax relief of RM2,000 (ONLY available for YA2013)
  • Reminder: Each unmarried child 18 years old and above, with certain condition as shown in picture below, has been increased to RM6,000 since YA2013.


You may also read our previous tax-related posts below:


10 Ekim 2014 Cuma

Budget 2015: The People's Economy... What's in it for YOU ?

The much awaited Budget 2015 was presented by our Prime Minister at Cabinet today. Looking on are hopeful Malaysians with their never ended wish lists, which already submitted via various channels. Does your wishes being addressed in the budget?


The People's Economy...


This is the title for Budget 2015, which referring to an economy that based on the daily lives of the rakyat. Very obvious, this is to address the concerns of the rakyat towards the implementation of GST soon.


What's in it?
Here, we only highlighting a few key points which related closely with most Malaysians:


  1. Several infrastructure projects will be implemented:
    • Sungai Besi - Ulu Klang Expressway (SUKE)
    • West Coast Expressway from Taiping to Banting
    • Damansara - Shah Alam Highway (DASH)
    • Eastern Klang Valley Expressway (EKVE)
    • East Coast railway line along Gemas-Mentakab, Jerantut-Sungai Yu and Gua Musang-Tumpat
    • 2nd MRT Line from Selayang to Putrajaya
    • LRT 3 Project, linking Bandar Utama to Shah Alam and Klang

  2. On GST, an additional lists of items that will not be subjected to GST as follows:


  3. In addition, GST free for electricity consumption be increased from the first 200 units to 300 units.

  4. No GST for the purchase of RON95 petrol, diesel and LPG
  5. YA2015 for individuals and households:
    • Individual income tax rates will be reduced by 1% - 3%
    • Tax payers with family and income of RM4,000 monthly will not have tax liability
    • The current 26% individual income tax will be reduced to 24%, 24.5% and 25%

  6. Corporate Tax:
    • YA2015: Cooperative income tax rate will reduced by 1% - 2%. Secretarial fee and tax filing fee are allowed as deduction
    • YA2016: Corporate income tax rate will be reduced to 24%
    • YA2016: Income tax for SMEs will also be reduced to 19%

  7. PTPTN Loan:
    • 10% rebate given to borrowers who continuously make repayments for 12 months until 31 December 2015.
    • 20% discount to borrowers who make lump sum repayments from now until 31st March 2015.

  8. Youth Housing Scheme... What's the terms and conditions ?
    • Smart partnership between Government, Bank Simpanan Nasional, EPF and Cagamas
    • For married youth aged between 25 - 40 years
    • Household income not exceeding RM10,000
    • Maximum funding for 1st home is RM500,000
    • Maximum loan period is 35 years
    • Government will provide monthly financial assistance of RM200 for first 2 years
    • 50% stamp duty exemption on instrument of transfer agreements and loan agreements
    • 10% loan guarantee to enable borrowers to obtain full financing including cost of insurance
    • Only for 20,000 units offered on a 'first come first serve basis'

  9. Goodies for students:
    • Jan 2015, RM100 each be given to all primary and secondary school students
    • 1Malaysia Book Voucher of RM250 per student

  10. Expenses incurred for treatment of serious diseases are given tax relief up to RM6,000 per year (from RM5,000 currently). This is available to tax payer, the spouse and children.

  11. Increase tax relief for each disabled child from RM5,000 to RM6,000

  12. Home ownership:
    • PR1MA with 80,000 units to be build
    • Ceiling of household income is raised from RM8,000 to RM10,000
    • Rent-To-Own scheme will be introduced specifically for individuals who are unable to obtain bank financing
    • Extending the 50% stamp duty exemption until 31st December 2016
    • Increase the purchase limit from RM400,000 to RM500,000
    • Skim Rumah Pertamaku with ceiling price raised to RM500,000, and age of borrowers to qualify for the scheme increased to 40 years old
  13. BR1M will be continue:
    • RM950 for households with monthly income of RM3,000 and below. It will be disbursed in 3 installments in Jan (RM300), May (RM300) and Sept 2015 (RM350)
    • RM750 for households with monthly income between RM3,000 and RM4,000. It will be disbursed in 3 installments in Jan (RM200), May (RM200) and Sept 2015 (RM350)
    • RM350 for single individuals aged 21 and above with monthly income not exceeding RM2,000.

  14. Half-month bonus for civil servants with minimum payment of RM500 to be paid in Jan 2015. Meanwhile, Government pensioners will also receive special financial assistance of RM250.


29 Nisan 2014 Salı

YA2013 Special Tax Relief ?


I know I know. This may sound too late for you, but I'm sure there are many of you out there are last-minute taxpayers. Even said so, for those of you already filed for your 2013 personal income recently, do you realized that there is this "Special Relief" ?

Example to show the stated "Special Relief" under tax summary page

What's that?
Am I entitle for it?

This special relief is given to those with chargeable income of less than RM96,000. This works out to be RM8,000 average monthly income. If you're earning less than that, for sure you're entitle for this special relief.


How much is that?
It was fixed at RM2,000 special relief to all qualified tax payers.


Happy e-filing ( I hope the system won't down...)

18 Aralık 2013 Çarşamba

25% Tax for Private Retirement Scheme (PRS) ?

Christmas is coming to town, but before that, it was also the time when many people are rushing to enroll/top up their Private Retirement Scheme (PRS). Why? Main reason is they want to enjoy the tax relief given of up to Rm3,000 per year. However, social media has over-took the whole atmosphere with the purported 25% tax on PRS. Is this true?


All I want for Christmas is Tax-Free...


Why suddenly got 25% tax? It was all started with the below video...


Anyway, some people had misunderstood the meaning and translated into such chaos in social media with more than few thousand likes and comments. Well, it seems like the respond garnered already impacting the PRS contributions for many people.


Since then, the Private Pension Administrator (PPA) which was set up to monitor and administer the whole PRS scheme, had issue a statement to clarify on this matter. Likewise, Inland Revenue Board (LHDN) also issue a statement on this matter. (Click here to view)

To summarize:


  1. NO tax on PRS withdrawal when contributor reaches the official retirement age set (currently at age 55)
  2. As per previous terms, 8% tax penalty will be imposed if contributor withdraw before retirement age.
  3. However, the 8% tax penalty will be exempted if:
    • In the event of Death;
    • Permanent departure from Malaysia;
    • Permanent total disablement (New addition);
    • Serious disease (New addition); or
    • Mental disability (New addition)
Gone are the so called bad news. Indeed, there is more good news with the 3 NEW pre-retirement withdrawal conditions. PRS contributors should feel relieve now.


Take the opportunity to invest before the closing date for respective PRS providers. You may refer to our previous article on PRS below:


23 Nisan 2013 Salı

How to get your PRS Tax Relief statement from PPA ? (April 2013)

In conjunction with the NEW tax relief available from YA2012, many Private Retirement Scheme (PRS) contributors are wondering how can they get the tax statement for income tax filling. To address your concern, here you go... (If you don't know what are we talking about, please find out "What is Private Retirement Scheme?")


To recap, contributions into a PRS scheme can enjoy a tax relief of up to RM3,000 from YA2012 - YA2021. If you did contribute some money into a PRS scheme in 2012, congratulations, you're entitled for PRS tax relief for YA2012. If you haven't, no worry, you still got time to start contributing before end of this year.

Back to the topic, please follow these few easy steps to get it:

Please surf www.ppa.my and click log in. I believe you already get your PIN from PPA when you made your first contribution. If not, please contact PPA and request again.


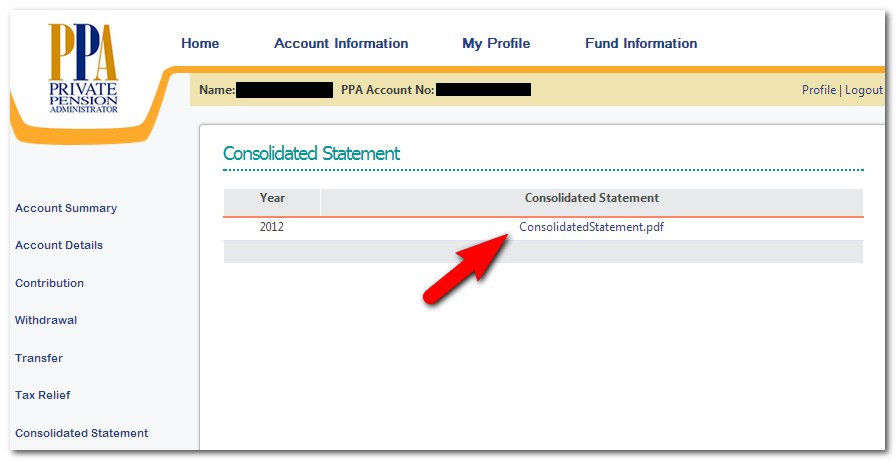
After log in, you will arrive at the following page. Supposedly, you can download the tax relief statement by clicking "Tax Relief".


However, you will be notified by this message.


Oppsss... What if I didn't keep the receipt or letter given by providers? No worry. Alternatively, you can download the "Consolidated Statement" as a proof and for income tax filling purpose. Hope this could clear your doubts. Happy income tax filing. Thanks.


Finance Malaysia would like to thank Alex Yeoh for his input in this article. Alex is a Licensed Financial Planner with VKA Wealth Planners, whom can advise and distribute multiple PRS products. You may contact him via email alexyeoh@vka.com.my

21 Nisan 2013 Pazar

Personal Income Tax for YA2012


Finance Malaysia hopes this article doesn't come late to give you some info on Personal Income Tax filling for year of assessment 2012. Maybe due to the general election, which had diverts our attention lately. Lol. Anyway, do remember to file your income tax before 30th April oh!!!

Well, here is the list of Personal Tax Relief for YA2012. And, I would like to highlight to you, in RED color words, some changes/differences from previous year.

Personal Tax Relief for YA2012
  • Item No.11:
    This would replace Item 10 from YA2012-YA2017 with higher amount of RM6,000
  • Item No.23:
    Private Retirement Scheme (PRS) is the NEW item which can help you reduce tax further with additional RM3,000 tax relief from YA2012-YA2021. As such, Item No.22 would be replaced until after YA2021.
All other items remained the same. Do reduce your tax payable by maximizing the tax relief amount. Remember to keep a record and file it properly. Happy tax filling. Thanks.

Blue color: Tax relief that we can adjust easily in our daily life
Green color: Tax relief for property not rented out with S&P signed between 10/03/09-31/12/10
Light red color: Tax relief related to child
Yellow color: Tax relief related to life insurance premium

19 Aralık 2012 Çarşamba

What are the TAX benefits from Private Retirement Scheme (PRS)?

According to Securities Commission of Malaysia, tax incentives are provided to both employers and individuals for the first 10 years from assessment year 2012; in addition to the tax deduction permitted for EPF contributions:
Amount of Tax Savings by individuals for PRS contributions
For Individual:
Tax relief of up to RM3,000 per year will be given for contributions made within that year. This is on top of existing tax relief already enjoyed by taxpayers. How much can you save from tax? Let's look at the table above which illustrates the amount of tax saving an individual get after personal tax relief and RM6,000 EPF + Life Insurance tax relief. Assuming maximum RM3,000 PRS relief, the amount of tax saving depends on your level of income. For high tax bracket individual, you can save up to RM780 annually!!!


For Employer:
Tax deduction on contributions to PRS made on behalf of their employees above the statutory rate of up to 19% of employees' remuneration was granted. Example, if an employer already making 12% EPF contributions to his employees, the employer may choose to reward their employees by contributing into employees PRS account for up to another 7%.


Vesting Schedule to Retain Employees?
Yes, employer can use PRS as a tool to retain employees by adding a "vesting schedule" clause. Currently, there are a few available vesting methods: by length of service, job rank, or by age. Unlike EPF, if an employee leaves before vesting, the employer can access to the un-vested portion of contribution already made. Likewise, for EPF, employee take the full amount when they left. With PRS vesting schedule, employee may think twice before switching jobs.

In conclusion, there are tax incentives for every tax payer, employee or employer. Ultimately, enough retirement funds was the key objective of PRS. On top of that, a tax exemption is also provided on income received by the funds under the PRS.


This is a guest post by Alex Yeoh in the series of Private Retirement Scheme. For more PRS info, you may contact Alex Yeoh (alexyeoh@vka.com.my), a licensed financial planner, whom can distributes products from multiple PRS providers. Thank you.

18 Aralık 2012 Salı

How Private Retirement Scheme (PRS) works actually?

Many people are still in the dark on how actually Private Retirement Scheme (PRS) works. In order to clear everyone's mind, we hope this post was timely for those who may want to entitle for extra tax relief of up to RM 3,000 given by PRS before 31st December 2012. To further explain the whole scheme, Finance Malaysia Blog was glad that Alex Yeoh, a licensed financial planner is able to share with us on this matter.


By Alex Yeoh,

First we must know that PRS is a voluntary scheme for the purpose of retirement saving. For ease of understanding, let us look at the picture above which explain the process into two parts. Initially, contributions were made by us into the PRS fund that we select. It was as flexible as  normal unit trust investments (shown in upper part). Contribute anytime any amount as you like, without any specific intervals. As simple as that.

When can I withdraw the money?
Each time, your contributions were split and maintained in sub-accounts A and B similar to EPF way (shown in lower part). 70% of contributions will go to Account A, which can be withdrawn upon reaching retirement age, which is currently at 55.

Meanwhile, the balance 30% into Account B, which can be withdrawn after one year, subject to 8% tax penalty. Take note that you can withdrawn from Account B for whatever reason. Although lump sum withdrawal are permitted, contributors are encouraged to retain their savings for continuous investment under the respective schemes.

Why 8% tax penalty?
The said 8% tax penalty was to discourage contributors to withdrawn their money prior to retirement age. We must understand that PRS is meant for retirement savings. Moreover, the 8% tax penalty was deducted from withdrawal amount to pay back Inland Revenue Board (IRB). Why? Because IRB is the one who gave you tax relief on contributions made initially. Otherwise, loop-hole was existed with everyone just want to take advantage of the tax relief and  withdrawn their money after that. Agree?

For more PRS info, you may contact Alex Yeoh (email: alexyeoh@vka.com.my), a licensed financial planner, whom can distributes products from multiple PRS providers. Thank you.